
YNAB
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
YNAB - Screenshots
Pros
- Clear budgeting system helps give every dollar a specific purpose.
- Bank syncing can reduce manual transaction entry.
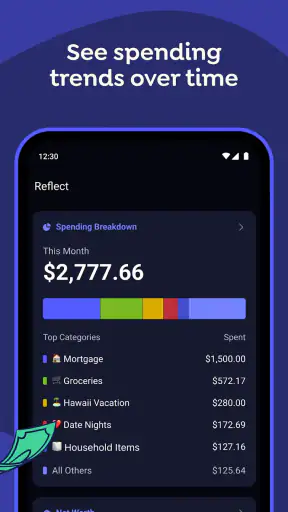
- Useful spending reports reveal habits and recurring expenses.
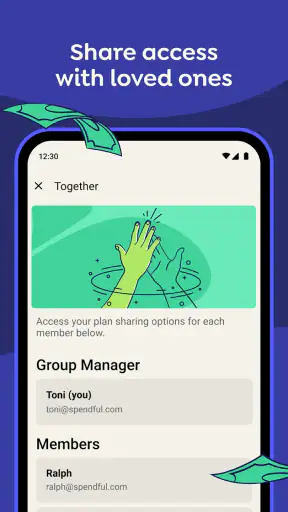
- Shared access makes household budgeting easier for couples or families.
- Helpful educational resources support users who are new to budgeting.
Cons
- The subscription cost may be difficult to justify for simple budgeting needs.
- Some bank connections can fail or require frequent reauthorization.
- Learning the envelope-style method takes time for first-time users.
- Limited investment and net-worth tools may require another financial app.
- Manual adjustments can be tedious when transactions are not imported correctly.
YNAB - Description
- App Name
- YNAB
- Package Name
- com.youneedabudget.evergreen.app
- Developer
- ynab.com
- Category
- Finance
- Last Updated
- Oct 20, 2015
- Version
- 26.32.0
When money decisions affect more than one person, a budgeting app has to do more than display a balance. It needs to make priorities visible without turning every grocery purchase into an argument. I spent time with YNAB as a finance app, focusing especially on how it fits into a household where two people share expenses, responsibilities, or a device. My overall impression is that it is most useful when everyone agrees to give each incoming amount a job before spending it.
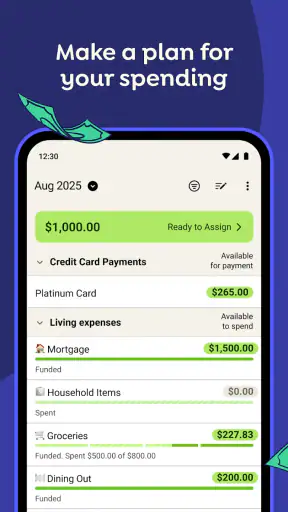
The central idea is deliberately hands-on. Instead of treating a budget as a report you check after the month has gone wrong, YNAB asks you to decide what available money should do now. That shift sounds small, but it changes the way I look at irregular bills, everyday spending, and the uncomfortable gap between what I want to buy and what I can actually afford.
How YNAB feels in a shared household
Imagine a couple managing rent, food, transport, subscriptions, and a child’s school costs from the same pool of income. One person opens the app before payday and assigns money to the bills that cannot move. The other checks the categories before ordering takeout or buying something for the home. The value is not that the app makes the decision for them; it gives both people a common language for the decision.
That is where this app feels different from a basic spending tracker. A traditional tracker may tell me that I spent too much on restaurants last month. YNAB is more useful earlier in the process: it encourages me to decide how much is available for restaurants before the purchase happens. If the category is short, the practical question becomes whether to wait, spend less, or move money from another priority.
For a shared household, this can reduce the vague feeling that “there should still be money somewhere.” The category plan becomes more meaningful than the bank balance because the balance may include rent money, annual insurance money, and grocery money all at once. Seeing those obligations separated helps me avoid treating every dollar in the account as casual spending money.
The app is also a reasonable fit for a person managing finances alone. I can imagine using it for personal bills, travel saving, debt payments, or a move. Still, its strongest personality appears when budgeting is an active routine rather than a passive record. Someone who only wants a quick monthly chart may find the method more involved than expected.
Starting without confusing the household
The first setup deserves patience. I would begin with the obligations that must be covered, then add flexible categories and longer-term goals. In a shared setting, I would avoid creating dozens of tiny categories immediately. A category for household supplies is easier to maintain than separate labels for every type of cleaning product, especially when both people are entering or reviewing transactions.
The useful boundary is between a category and a person. Categories should describe what the money is for, not who is allowed to spend it. If one partner handles transport and the other handles groceries, that division can be discussed separately. Turning every responsibility into a rigid budget wall may create more friction than clarity.
I would also agree on naming before inviting another person into the routine. “Home,” “household,” and “miscellaneous” can mean different things to different people. Clear labels such as “weekly groceries,” “annual renewals,” or “medical buffer” make the plan easier to understand when someone else opens it without needing a long explanation.
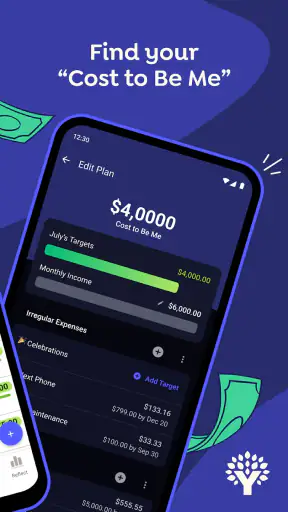
One of the less obvious lessons is that a budget should reflect timing, not only totals. A yearly bill can be affordable in total and still cause trouble when it arrives in one month. I found the planning approach more helpful when I treated those future costs as present responsibilities. That makes the budget feel less optimistic and more connected to real life.
Coordinating purchases and changes
Shared budgeting works best when people agree on a simple transaction routine. If one person spends from a category, that purchase should be recorded or reviewed promptly enough that the remaining amount still means something. Waiting until the end of the week can make the app look healthier than the bank account and creates avoidable confusion.
A realistic example is a supermarket trip. I might see that the food category has enough for the planned shop, but then add household items at the checkout. The correct response is not to pretend the extra purchase belongs elsewhere. I would record it honestly and, if necessary, move money from a less urgent category. That small act preserves the usefulness of the plan.
Moving money between categories is not a failure. In my experience, it is one of the main ways a budget responds to real life. The important question is what priority is being reduced. If money moves from entertainment to groceries, that tells the household something. If it moves repeatedly from bills to impulse spending, the pattern deserves a conversation rather than another silent adjustment.
For shared use, I would establish a short weekly check-in. It does not need to become a formal meeting. A few minutes can be enough to look at upcoming bills, unusually large purchases, and categories that are running low. This is more effective than expecting the app to resolve disagreements automatically. YNAB can show the plan, but the household still has to decide together.
Another practical tip is to separate predictable shared commitments from personal discretionary spending. If both people have individual purchases, giving those expenses their own agreed space can make the joint plan feel less intrusive. It also avoids the common mistake of treating every personal purchase as a household debate.
Boundaries, trust, and younger users
Because this is a finance app, trust matters more than visual polish. I would not hand a child or an inexperienced household member full responsibility for the budget without first explaining what the categories mean and which decisions require discussion. The app can support a shared process, but it should not replace financial judgment or adult supervision.
The age rating is Everyone, which makes the app broadly accessible from an age-label perspective. That does not mean every budgeting role is suitable for every age. A younger user could learn useful habits by helping with a simple grocery category or a savings goal, while account ownership, bill planning, and sensitive financial decisions should remain with the responsible adult.
I would also be careful about account boundaries. A shared device does not automatically mean every person should see every financial detail. Before using the app together, the household should decide who needs access, what information is comfortable to share, and who is responsible for correcting mistakes. Those are relationship and privacy decisions, not features I would assume the app can solve for me.
For partners, transparency can be healthy when it is mutual and agreed upon. It becomes uncomfortable when one person uses the budget as a tool for surveillance or criticism. I see YNAB as a planning workspace, not a scorecard. The best conversations focus on priorities and trade-offs rather than blaming the person who spent the money.
What the app does well, and where it asks more from me
YNAB is developed by ynab.com and sits firmly in the finance category. It is free to install, with in-app purchases listed from $14.99 to $109.00 per item, so I would check the current purchase terms carefully before committing. The app has an Everyone content rating and has been available since October 20, 2015. Its current version is 26.32.0 and it requires iOS 11 or later.
Its public reception suggests that many people find the method worthwhile: the app has a 4.6 average from around 25 thousand ratings, with more than 4 thousand written reviews, and it has passed one million installs. Those figures do not decide whether it will suit me, but they do show that this is an established budgeting tool rather than a new experiment.
The strongest part is the active planning mindset. I am not merely collecting receipts after the fact. I am forced to confront competing priorities while money is still available. That makes the app particularly useful for irregular income, lumpy annual expenses, or households that repeatedly spend money intended for something else.
The trade-off is effort. YNAB rewards regular attention, accurate categorization, and a willingness to adjust the plan. If I dislike assigning money, checking categories, or revisiting decisions, the experience may feel like work. A simpler expense tracker could be better for someone who mainly wants a visual record and has little interest in managing spending through categories.
The app can also feel demanding during a financially stressful month. When every category is tight, moving money around may expose difficult choices rather than make them disappear. I consider that an honest strength, but it is not always comfortable. A polished dashboard that hides the shortfall may feel easier in the moment, while YNAB makes me deal with the shortfall directly.
Compared with a spreadsheet, YNAB is more approachable for repeated day-to-day budgeting because the structure is already there. A spreadsheet can be more flexible, especially for unusual household arrangements or custom calculations, but it also depends heavily on discipline and design. Compared with automatic banking summaries, YNAB is less passive and more intentional. Those summaries are convenient for seeing where money went; this app is better suited to deciding where available money should go next.
Questions I would settle before using it
If I were deciding whether to use it with another person, my first question would be whether both people are willing to participate. One enthusiastic user can build the plan, but the system becomes unreliable if the other person regularly spends without recording purchases or ignores category limits. The app cannot create cooperation where there is none.
I would also ask whether the household has enough flexibility to make category decisions meaningful. Even with a careful plan, there may be months when all available money is already committed to essentials. YNAB can clarify that reality and help prioritize, but it cannot manufacture extra income. Someone looking for borrowing, investing, tax filing, or bill negotiation should not mistake this budgeting tool for a complete financial service.
Another question is whether the method fits the way income arrives. People paid on a regular schedule may find the routine straightforward. Freelancers, seasonal workers, and households with uneven income may benefit from the emphasis on using available money carefully, but they should expect more active planning when deposits vary. I would start with a small number of essential categories and refine the system after seeing how actual income behaves.
I would finally decide how much detail is useful. More categories are not automatically better. If the household spends more time debating labels than making decisions, the structure has become too complicated. I prefer categories that answer a real question: can we afford this, what is this money reserved for, and which priority changes if we spend it?
My household verdict
For a shared household, I recommend YNAB when the goal is coordination rather than surveillance. It gives partners or family members a practical place to discuss upcoming obligations, discretionary spending, and trade-offs. The method is especially compelling for people who feel that their bank balance looks healthy until several bills arrive at once.
I would skip it if I wanted a completely automatic experience, a simple receipt archive, or a service that handles broader financial tasks beyond budgeting. I would also hesitate if the other people sharing expenses are unwilling to follow the same transaction habits. In that situation, a simpler personal tracker may create less conflict, even if it offers less planning depth.
My best advice is to begin modestly: define the household’s essential categories, agree on who reviews purchases, and schedule a short check-in before adding detailed goals. Use category changes to explain priorities, not to assign blame. That approach lets the app support trust instead of putting pressure on it.
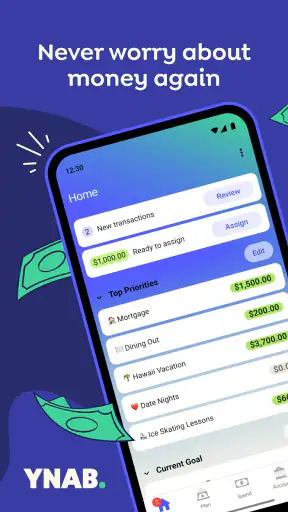
After using it, I see the store summary, “Never worry about money again,” as an aspiration rather than a promise. Money can still be tight, unexpected costs can still happen, and people can still disagree. What YNAB gives me is something more practical: a clearer way to decide what the available money needs to do, together with a visible record of the choices. For households prepared to stay involved, that clarity is the app’s real advantage.
FAQ
What is YNAB and how does it work?
YNAB, short for You Need A Budget, is a personal budgeting app designed around assigning every dollar a specific job. Instead of simply tracking past spending, it encourages you to plan for bills, savings, debt payments, and everyday expenses before you spend. The app syncs your budget across devices and provides reports, spending categories, account balances, and progress features to help you make more deliberate financial decisions.
Is YNAB free to download and use?
YNAB can usually be downloaded for free, but continued access requires a paid subscription after the trial period. The subscription unlocks the complete budgeting system, account synchronization, reports, goal features, and access across supported devices. Pricing can vary by region and may change, so it is worth checking the current details in the official app store or on YNAB’s website before starting a trial.
Can YNAB connect to my bank accounts?
YNAB supports bank synchronization with many financial institutions, allowing transactions and account balances to be imported into your budget. Availability and reliability depend on your country, bank, and the connection provider used. Some accounts may require manual entry or file import if automatic syncing is unavailable. Even with synchronization enabled, reviewing imported transactions regularly is recommended to keep your budget accurate.
Is YNAB suitable for beginners who have never budgeted before?
YNAB can be a good choice for beginners, although its envelope-style method requires active participation and may feel different from a simple expense tracker. The app guides users through creating categories, assigning available money, handling overspending, and planning for future expenses. New users should expect a learning period and benefit from using the built-in guidance, tutorials, and regular budget reviews.
Is my financial information safe when using YNAB?
YNAB uses security measures intended to protect account and financial information, including encrypted connections and authentication controls. However, no online service can eliminate every possible security risk. Users should create a strong, unique password, enable available security features, keep the app updated, and avoid entering sensitive information on unfamiliar websites. Before connecting a bank, review YNAB’s current privacy and security policies.


